This table covers the nine municipalities of the Belgian coast, from De Panne to Knokke. It relies on their 2026-2031 tax regulations and on six written confirmations from the municipalities. For permits and registration, see our guide to Airbnb regulations on the Belgian coast.
Is there really a tourist tax on the Belgian coast?
Not in the sense of an amount per night and per guest. The 2026-2031 regulations of the nine municipalities, read in full, set a flat annual charge per property. The municipality sends it to the taxpayer as a tax assessment notice (aanslagbiljet). The number of nights sold makes no difference.
Two taxes coexist. The lodging tax targets the operation of a tourist accommodation; Ostend calls it verblijfsbelasting. The second-residence tax (tweede verblijven) targets any property with nobody registered as resident on 1 January. De Panne justifies it this way: these owners do not pay the municipal surcharge on personal income tax.
The platform does not matter. Knokke-Heist classifies a property by its name and its own facilities (article 1, 12° of the lodging tax regulation). The booking channel is not mentioned: Airbnb is not a tax category.
How much does a holiday let pay in each of the 9 municipalities in 2026?
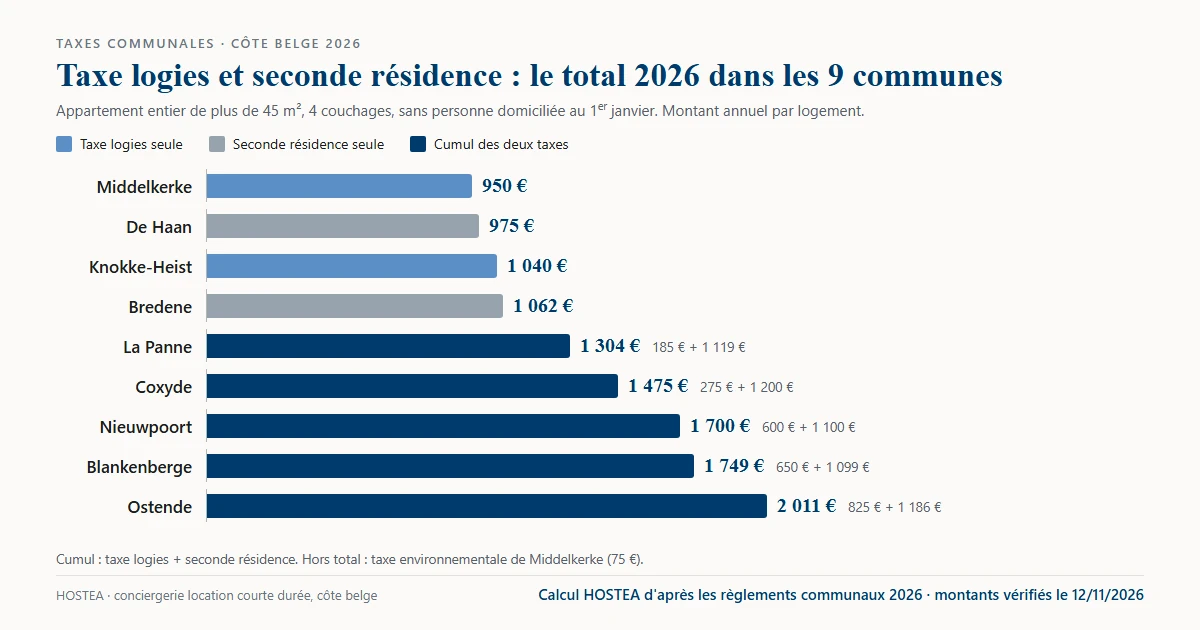
Between €950 and €2,011 a year, depending on the municipality and its mechanism. Reference case: a whole flat over 45 m², 4 beds, nobody registered as resident on 1 January. It is registered with Toerisme Vlaanderen and offered all year round. One bed counts as one person.
| Municipality | Mechanism and legal basis | Lodging tax | Second-residence tax | 2026 total | Details |
|---|---|---|---|---|---|
| Middelkerke | Lodging tax only (art. 2, second-residence tax regulation) | €950 | Excluded | €950 | the Middelkerke municipal regulation |
| De Haan | Second-residence tax only (art. 9, second-residence tax regulation) | Excluded | €975 | €975 | letting a holiday home in De Haan |
| Knokke-Heist | Lodging tax only (art. 3 § 5, lodging tax regulation) | €1,040 | Excluded | €1,040 | the per-bed tax in Knokke-Heist |
| Bredene | Second-residence tax only (art. 7, lodging tax regulation) | Excluded | €1,062 | €1,062 | the rules and taxes in Bredene |
| De Panne | Both taxes (art. 3, second-residence tax regulation) | €185 | €1,119 | €1,304 | permits, zones and taxes in De Panne |
| Koksijde | Both taxes, new in 2026 (art. 1, second-residence tax regulation) | €275 | €1,200 | €1,475 | both taxes combined in Koksijde |
| Nieuwpoort | Both taxes (confirmed in writing by the town on 15/09/2026) | €600 | €1,100 | €1,700 | taxes and planning in Nieuwpoort |
| Blankenberge | Both taxes (preamble of the second-residence tax regulation) | €650 | €1,099 | €1,749 | registration and taxes in Blankenberge |
| Ostend | Both taxes (confirmed in writing by the city on 16/09/2026) | €825 | €1,186 | €2,011 | holiday rental rules in Ostend |
Amounts checked on 12/11/2026 in the 2026-2031 regulations listed in the sources, with the date of each municipal council decision. Totals added up by HOSTEA. Not included: Middelkerke's environmental tax, €75 per property, let or not (regulation of 17/12/2025).
Remember two groups: under €1,100 in the four single-tax municipalities, €1,304 to €2,011 in the five that charge both. Double taxation widens the gap far more than the rate of each tax.
What about 6 or 8 beds?
The ranking shifts: four municipalities tax by capacity band, Knokke-Heist per bed. HOSTEA calculation, same reference case:
| Municipality | 4 beds | 6 beds | 8 beds |
|---|---|---|---|
| Middelkerke | €950 | €950 | €950 |
| De Haan | €975 | €975 | €975 |
| Knokke-Heist | €1,040 | €1,560 | €2,080 |
| Bredene | €1,062 | €1,062 | €1,062 |
| De Panne | €1,304 | €1,304 | €1,488 |
| Koksijde | €1,475 | €1,475 | €1,560 |
| Nieuwpoort | €1,700 | €1,700 | €2,300 |
| Blankenberge | €1,749 | €1,749 | €2,099 |
| Ostend | €2,011 | €2,011 | €2,011 |
Knokke-Heist charges €260 per bed, with a minimum of €1,040 (article 4). In De Panne, Koksijde, Nieuwpoort and Blankenberge, the higher band starts at 7 people. At 8 beds, Nieuwpoort therefore moves to the top with €2,300.
Three special cases change the figure:
- Floor area: the second-residence tax drops below a threshold. Up to 45 m² in De Panne (€883), up to 40 m² in Koksijde (€980), under 40 m² in Nieuwpoort (€1,015).
- Ostend's occasional scheme: offered 120 days a year at most, €275 of lodging tax, €1,461 in total. This rate authorises nothing: check the number of letting days allowed in Flanders.
- An unregistered property in Knokke-Heist: double rate, €520 per bed, minimum €2,080 (article 4).
And in 2027?
Six municipalities already make it possible to calculate the 2027 amount at 4 beds. De Panne: €1,337. Knokke-Heist: €1,040. Middelkerke: €950. Nieuwpoort: €1,700, frozen until 2031 unless the council votes again (written reply of 15/09/2026). Bredene: €1,094. Koksijde: €1,512, using the formula in its regulation (HOSTEA calculation). In De Haan, Blankenberge and Ostend, the 2027 indexation has not been published yet.
Already paying the second-residence tax: how much more does letting cost?
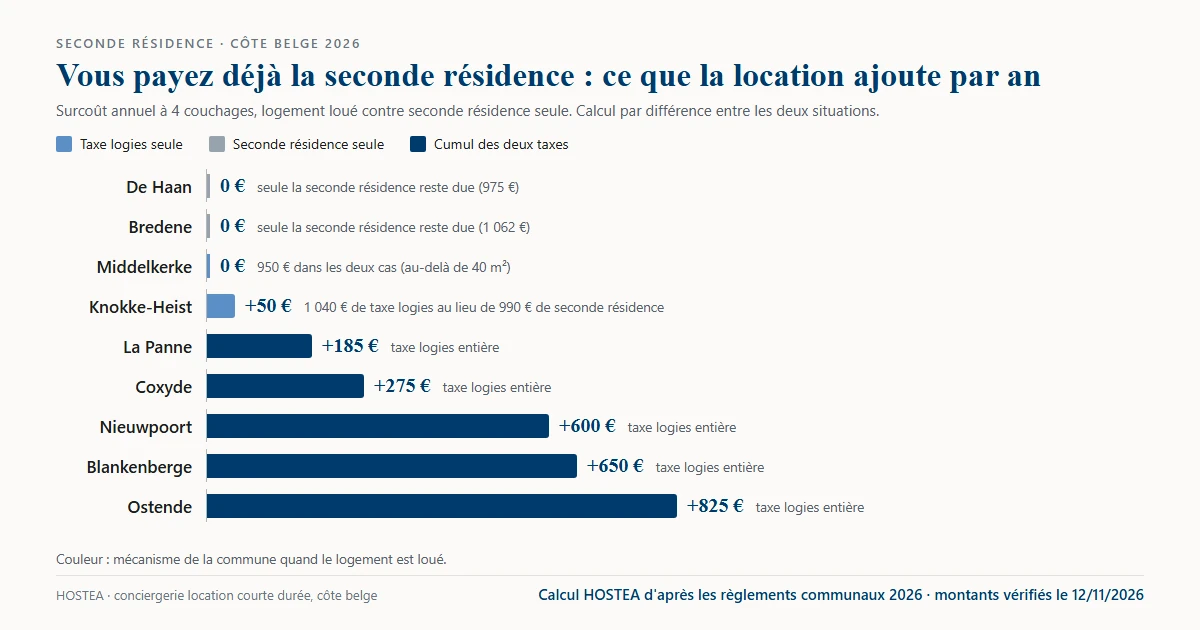
From €0 to €825 more a year, at 4 beds. A second home used by its owner already pays this tax in all nine municipalities. Letting adds the lodging tax, except where an article rules it out. HOSTEA calculation, comparing the two situations:
- €0 in De Haan and Bredene, where only the second-residence tax remains due (€975 and €1,062).
- €0 in Middelkerke above 40 m²: €950 in both cases. A studio of 40 m² or less pays €100 more.
- €50 in Knokke-Heist, where €1,040 of lodging tax replaces €990 of second-residence tax.
- The full lodging tax elsewhere: €185 in De Panne, €275 in Koksijde, €600 in Nieuwpoort, €650 in Blankenberge, €825 in Ostend.
Each difference rests on an article, cited in the "Mechanism and legal basis" column of the first table. Middelkerke, for example, excludes from the second-residence tax the units of a "logiesverstrekkend bedrijf", an accommodation business. In the five other municipalities, no article rules out double taxation.
Who pays, and do you need to declare anything to the municipality?
The second-residence tax is due from the owner on 1 January, in all nine second-residence tax regulations we read. Where there is a usufruct, surface right or emphyteutic lease, it targets the holder of that right. De Panne, Blankenberge and De Haan specify that it remains due when the property is let.
The lodging tax targets the operator, with the owner jointly and severally liable or presumed to be the operator depending on the municipality. Knokke-Heist also makes the intermediary jointly and severally liable for payment (article 3 § 2). Ostend taxes the owner and provides for joint and several liability in case of non-payment (written reply from the city of 16/09/2026).
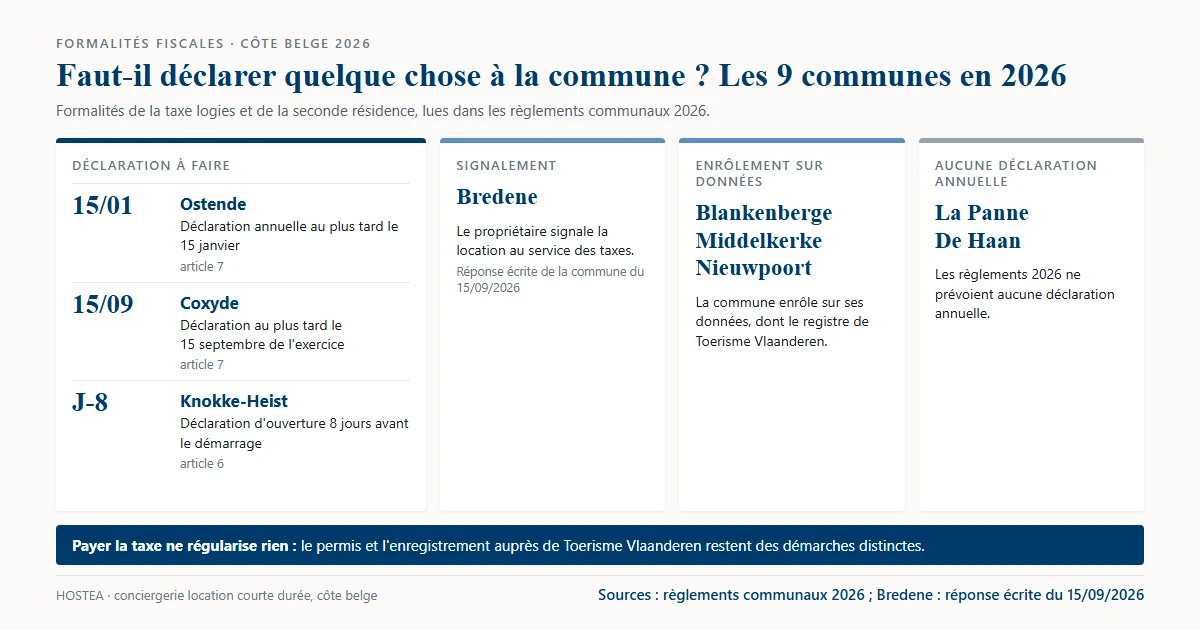
Formalities vary from one municipality to another:
- Ostend: annual declaration by 15 January at the latest (article 7). The city's web page (12/11/2026) calls it "valid until revoked": we follow the regulation, so check with the tax department.
- Koksijde: declaration by 15 September of the tax year at the latest (article 7).
- Knokke-Heist: opening declaration 8 days before starting (article 6).
- Bredene: the owner reports the letting to the tax department (written reply of 15/09/2026).
- Blankenberge, Middelkerke and Nieuwpoort: assessment based on the municipality's data, including the Toerisme Vlaanderen register.
- De Panne and De Haan: no annual declaration in the 2026 regulations.
Penalties only exist where the regulation provides for them. Ostend increases the tax by 50%, then by 100% for a second offence (article 8). It also provides for fines of €90 and €250 (article 9). Koksijde adds 25% (article 9). The regulations of the seven other municipalities provide for none.
Paying the tax regularises nothing: Ostend, Koksijde, Nieuwpoort, Blankenberge and Knokke-Heist make it due even without a permit. The permit and registration remain separate steps: see how to get your Logiesdecreet registration number.
Can you pass the tax on to guests?
Yes, within the limits set by some municipalities. You remain free to set your nightly rate. Four regulations give a benchmark:
- Ostend: at most €4.72 excl. VAT per unit per night (article 3).
- Blankenberge: at most €2.50 per person per night, once per stay (article 6).
- Knokke-Heist: €2.00 incl. VAT per night per tourist, deemed moderate (preamble, not a cap).
- De Panne: €1 per person per night on average, deemed moderate (preamble).
Nieuwpoort allows the tax to be passed on "naar billijkheid", meaning fairly, without an amount; the other regulations we read set nothing. The VAT treatment of this surcharge is not a municipal matter. It depends on the services provided with the rental (FPS Finance, 2022 FAQ on furnished accommodation). Have it checked by your accountant before applying it.
Who can handle these formalities for you?
A property management company can prepare and send the declaration, but it does not pay the tax for you. That is the purpose of HOSTEA Commun', our municipal formalities service, available without a management agreement. You can hand over the declaration and follow-up of your municipal taxes to HOSTEA Commun' :
- Declaration (Ostend, Koksijde, Knokke-Heist): we draft it and send it on time.
- Assessment from records (Blankenberge, Middelkerke, Nieuwpoort, Knokke-Heist): we check the Flemish register data on your property. The recorded capacity sets the band in Blankenberge and Nieuwpoort. In Knokke-Heist, it sets the per-bed amount and counts as a presumption unless proven otherwise (article 4 § 3). Middelkerke applies a flat amount per holiday home, whatever its capacity (article 4).
- Bredene: the report contains your national register number. We prepare the text, you send it.
Municipal tax declaration: €40 incl. VAT, free if a management agreement is signed before filing. You remain the taxpayer wherever the regulation designates you. Have the amount and taxpayer confirmed by the municipality, then your situation by an accountant or a tax lawyer.
Frequently asked questions
Is the tax due if my property was not let all year?
Does paying the tax make my rental legal?
What happens if my property is not registered with Toerisme Vlaanderen?
Can a property management company declare the municipal tax for me?
Further reading
Sources
- Gemeente De Panne, belasting op de toeristische logies and belasting op de tweede verblijven, municipal council of 15/12/2025, tax years 2026 to 2031 (lodging tax: articles 3 and 4, preamble; second-residence tax: articles 2 to 4, preamble), pages accessed on 12/11/2026: https://www.depanne.be/nl/belasting-toeristisch-logies and https://www.depanne.be/nl/belasting-op-de-tweede-verblijven
- Gemeente Koksijde, belasting op exploiteren van kamergerelateerde toeristische logies (articles 1, 4, 7 and 9) and belasting op tweede verblijven (articles 1 and 4), municipal council of 15/12/2025, list of taxes accessed on 12/11/2026: https://koksijde-echo.cipalschaubroeck.be/raadpleegomgeving/zittingen/3ff9b6d9-07ac-458b-922b-ebf72fad311a/agendapunten/14fd225b-d5f9-42c8-89be-8d572a5dc172 and https://koksijde-echo.cipalschaubroeck.be/raadpleegomgeving/zittingen/3ff9b6d9-07ac-458b-922b-ebf72fad311a/agendapunten/cc5d75e7-922e-4478-bf4a-a129528012c5
- Stad Nieuwpoort, belasting op kamergerelateerde logies (articles 4 and 7, preamble) and belasting op de tweede verblijven, municipal council of 21/08/2025, list of regulations accessed on 12/11/2026: https://www.nieuwpoort.be/belasting-op-het-verstrekken-van-logies and https://www.nieuwpoort.be/bekendmakingen/detail/1644/belasting-op-de-tweede-verblijven-aj2026-t-e-m-2031
- Gemeente Middelkerke, exploiteren van toeristische logies, tweede verblijven (article 2) and algemene milieubelasting, municipal council of 17/12/2025, texts reread on 12/11/2026: https://publicaties.middelkerke.be/reglementen/Exploiterentoeristischelogies203.html, https://publicaties.middelkerke.be/reglementen/Tweedeverblijven1.html and https://publicaties.middelkerke.be/reglementen/Algemenemilieubelasting.html
- Stad Oostende, verblijfsbelasting, municipal council of 27/04/2026 (articles 2, 3, 7, 8 and 9), page accessed on 12/11/2026: https://www.oostende.be/verblijfsbelasting and regulation https://www.oostende.be/file/download/4c01f878-d5ed-474b-854e-79c5d76e2c0a/izsZKGQstnwWO6jTR6CLeDdPj1NuaQJb6iKokms4nA3d.pdf; belasting op de tweede verblijven, municipal council of 13/12/2025: https://www.oostende.be/file/download/64dc9b04-43ad-47f5-bd2f-537555d2298c/RjBmFzMaV3KhpoIVPyXGzIixI8yaRjMULcZQJHuZg3d.pdf
- Gemeente Bredene, belasting op het verhuren van een verhuureenheid in kamergerelateerde logies (article 7) and belasting op tweede verblijven, municipal council of 18/12/2025, regulations linked from the tax page accessed on 12/11/2026: https://www.bredene.be/sites/default/files/2025-12/belastingreglement-op-het-verhuren-van-een-verhuureenheid-in-kamergerelateerde-logies-AJ-2026-2031-GR-18-12-2025.pdf and https://www.bredene.be/sites/default/files/2025-12/belastingreglement-2e-VB-2026-2031-GR-18-12-2025.pdf
- Gemeente De Haan, gemeentebelasting tweede verblijven (articles 4 and 9) and kamergerelateerde logies 2026-2031, municipal council of 18/12/2025, list of taxes accessed on 12/11/2026: https://www.dehaan.be/gemeentebelasting-tweede-verblijven-2026-2031 and https://www.dehaan.be/gemeentebelasting-verhuren-van-een-eenheid-in-kamergerelateerde-logies-2026-2031
- Stad Blankenberge, belasting op het logies (articles 3, 4, 6 and 9) and belasting op de tweede verblijven (articles 5 and 6, preamble), municipal council of 16/12/2025, list of regulations accessed on 12/11/2026: https://www.blankenberge.be/belasting-op-het-logies-gr-16122025 and https://www.blankenberge.be/belasting-op-de-tweede-verblijven-gr-16122025
- Gemeente Knokke-Heist, belasting op het verstrekken van toeristische logies, municipal council of 27/11/2025 (articles 1, 3, 4 and 6, preamble), reread online on 12/11/2026: https://www.knokke-heist.be/sites/default/files/paragraph-file/Uittreksels%20individueel%20-%202025-12-02T114700.379.pdf; belasting op de tweede verblijven, municipal council of 26/02/2026: https://www.knokke-heist.be/sites/default/files/paragraph-file/Uittreksels%20individueel%20-%202026-03-03T114837.658_0.pdf
- Written replies to HOSTEA: Ontvangsten department of Knokke-Heist (08/07/2026), finance department of Bredene (11/09/2026 and 15/09/2026), planning department of De Haan (11/09/2026), Team Financiën of De Panne (11/09/2026), finance department of Nieuwpoort (15/09/2026), tax department of Ostend (16/09/2026).
- Toerisme Vlaanderen, "Je logies aanmelden", accessed on 12/11/2026: https://www.toerismevlaanderen.be/nl/logies/aanmelding
- FPS Finance (SPF Finances), FAQ "Fourniture des logements meublés : modification importante à partir du 1er juillet 2022", accessed on 12/11/2026: https://fin.belgium.be/sites/default/files/media/documents/fourniture-logements-meubles-taxation-tva.pdf
This article is for information only and does not replace professional advice. Have the amounts and the taxpayer for your property confirmed by the municipality, and your situation checked by an accountant, before any decision.